
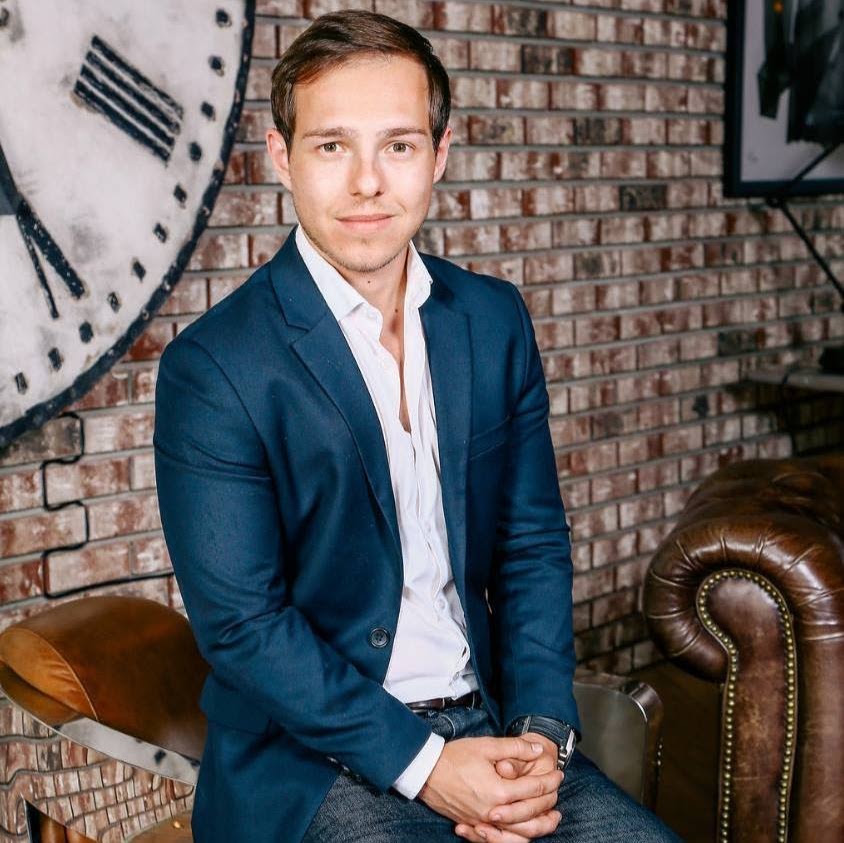
Graham Stephan
As a 34 year old real estate investor who started working in real estate shortly after turning 18, with over $120,000,000 in residential sales since 2008, I've created this channel to share my successes, failures, and experiences in real estate, personal finance, and investing news. I'm also obsessed with frugality and credit card churning...a lot. So Subscribe! Because all the cool kids are doing it. Feel free to follow me on Snapchat / Instagram: GPStephan
Past bets that played out
These are the clearest thesis calls with observable outcomes, linked back to the original videos.
Content argues (citing Morgan Stanley/Harvard-style framing) that the US housing market is in a long-term “reset,” not a 2008 crash: affordability stays poor, inventory remains constrained due to the mortgage “lock-in effect,” turnover is extremely low, and prices may keep grinding higher despite weak demand. Implication: existing-home transaction ecosystem may stay pressured, while new-home builders can take share because they can add supply and use incentives to move product.
Content argues (citing Morgan Stanley/Harvard-style framing) that the US housing market is in a long-term “reset,” not a 2008 crash: affordability stays poor, inventory remains constrained due to the mortgage “lock-in effect,” turnover is extremely low, and prices may keep grinding higher despite weak demand. Implication: existing-home transaction ecosystem may stay pressured, while new-home builders can take share because they can add supply and use incentives to move product.
Content argues (citing Morgan Stanley/Harvard-style framing) that the US housing market is in a long-term “reset,” not a 2008 crash: affordability stays poor, inventory remains constrained due to the mortgage “lock-in effect,” turnover is extremely low, and prices may keep grinding higher despite weak demand. Implication: existing-home transaction ecosystem may stay pressured, while new-home builders can take share because they can add supply and use incentives to move product.
What this channel is watching now
Recent mentions show where this author is concentrating attention right now.
Latest videos and market context
Recent source posts from this author. Create an account to inspect the complete persisted research trail.
Ben Mallah Talks To Homeless Before Property Inspection 😭
Ben Mallah's Private Jet Disaster...
I Paid Off My 2.875% Mortgage…Dave Ramsey Was Right
I Got Audited by AI
Proof-backed call history
These are recent thesis calls tied to original source content where available.
Content argues (citing Morgan Stanley/Harvard-style framing) that the US housing market is in a long-term “reset,” not a 2008 crash: affordability stays poor, inventory remains constrained due to the mortgage “lock-in effect,” turnover is extremely low, and prices may keep grinding higher despite weak demand. Implication: existing-home transaction ecosystem may stay pressured, while new-home builders can take share because they can add supply and use incentives to move product.
Content argues (citing Morgan Stanley/Harvard-style framing) that the US housing market is in a long-term “reset,” not a 2008 crash: affordability stays poor, inventory remains constrained due to the mortgage “lock-in effect,” turnover is extremely low, and prices may keep grinding higher despite weak demand. Implication: existing-home transaction ecosystem may stay pressured, while new-home builders can take share because they can add supply and use incentives to move product.
Content argues (citing Morgan Stanley/Harvard-style framing) that the US housing market is in a long-term “reset,” not a 2008 crash: affordability stays poor, inventory remains constrained due to the mortgage “lock-in effect,” turnover is extremely low, and prices may keep grinding higher despite weak demand. Implication: existing-home transaction ecosystem may stay pressured, while new-home builders can take share because they can add supply and use incentives to move product.
Content argues (citing Morgan Stanley/Harvard-style framing) that the US housing market is in a long-term “reset,” not a 2008 crash: affordability stays poor, inventory remains constrained due to the mortgage “lock-in effect,” turnover is extremely low, and prices may keep grinding higher despite weak demand. Implication: existing-home transaction ecosystem may stay pressured, while new-home builders can take share because they can add supply and use incentives to move product.
Content argues (citing Morgan Stanley/Harvard-style framing) that the US housing market is in a long-term “reset,” not a 2008 crash: affordability stays poor, inventory remains constrained due to the mortgage “lock-in effect,” turnover is extremely low, and prices may keep grinding higher despite weak demand. Implication: existing-home transaction ecosystem may stay pressured, while new-home builders can take share because they can add supply and use incentives to move product.
Content argues (citing Morgan Stanley/Harvard-style framing) that the US housing market is in a long-term “reset,” not a 2008 crash: affordability stays poor, inventory remains constrained due to the mortgage “lock-in effect,” turnover is extremely low, and prices may keep grinding higher despite weak demand. Implication: existing-home transaction ecosystem may stay pressured, while new-home builders can take share because they can add supply and use incentives to move product.
Content argues (citing Morgan Stanley/Harvard-style framing) that the US housing market is in a long-term “reset,” not a 2008 crash: affordability stays poor, inventory remains constrained due to the mortgage “lock-in effect,” turnover is extremely low, and prices may keep grinding higher despite weak demand. Implication: existing-home transaction ecosystem may stay pressured, while new-home builders can take share because they can add supply and use incentives to move product.
The source claims a sharp downturn/collapse in China’s housing market driven by high leverage, presales, buyer confidence loss, developer defaults, and knock-on effects to banks, local government revenue, commodities, and globally exposed consumer/luxury firms. It is high-level and sensational, with limited verifiable data points, but it maps to known China property stress channels and yields tradable macro/sector expressions via liquid ETFs and large-cap global cyclicals.
The source claims a sharp downturn/collapse in China’s housing market driven by high leverage, presales, buyer confidence loss, developer defaults, and knock-on effects to banks, local government revenue, commodities, and globally exposed consumer/luxury firms. It is high-level and sensational, with limited verifiable data points, but it maps to known China property stress channels and yields tradable macro/sector expressions via liquid ETFs and large-cap global cyclicals.
The source claims a sharp downturn/collapse in China’s housing market driven by high leverage, presales, buyer confidence loss, developer defaults, and knock-on effects to banks, local government revenue, commodities, and globally exposed consumer/luxury firms. It is high-level and sensational, with limited verifiable data points, but it maps to known China property stress channels and yields tradable macro/sector expressions via liquid ETFs and large-cap global cyclicals.
The source claims a sharp downturn/collapse in China’s housing market driven by high leverage, presales, buyer confidence loss, developer defaults, and knock-on effects to banks, local government revenue, commodities, and globally exposed consumer/luxury firms. It is high-level and sensational, with limited verifiable data points, but it maps to known China property stress channels and yields tradable macro/sector expressions via liquid ETFs and large-cap global cyclicals.
The source claims a sharp downturn/collapse in China’s housing market driven by high leverage, presales, buyer confidence loss, developer defaults, and knock-on effects to banks, local government revenue, commodities, and globally exposed consumer/luxury firms. It is high-level and sensational, with limited verifiable data points, but it maps to known China property stress channels and yields tradable macro/sector expressions via liquid ETFs and large-cap global cyclicals.
About this channel
Channel bio, source link, and public-market context from YouTube.
As a 34 year old real estate investor who started working in real estate shortly after turning 18, with over $120,000,000 in residential sales since 2008, I've created this channel to share my successes, failures, and experiences in real estate, personal finance, and investing news. I'm also obsessed with frugality and credit card churning...a lot. So Subscribe! Because all the cool kids are doing it. Feel free to follow me on Snapchat / Instagram: GPStephan
Most recognized assets
Unlock the full track record
Create an account to inspect the complete author history, trust-weighted rankings, and persisted research across authors, theses, and assets.
69 more thesis calls are available after sign-up.